- Published on
From Event Detection to Financial Labels
Financial labels depend on when an event begins, how its horizon is set, and which outcome is observed first. The notebooks move from volatility-scaled event detection to triple-barrier outcomes, meta-labels, and trend-scanning labels.
The central relation
A three-barrier label records which stopping event occurs first:
identifies an event. The upper and lower barriers are scaled by information available when the event begins, and the time barrier sets the maximum horizon. The label depends on the first observed crossing.
How market events become prediction labels
The public-data examples show the price and volatility inputs and then display the realized first-touch outcomes.
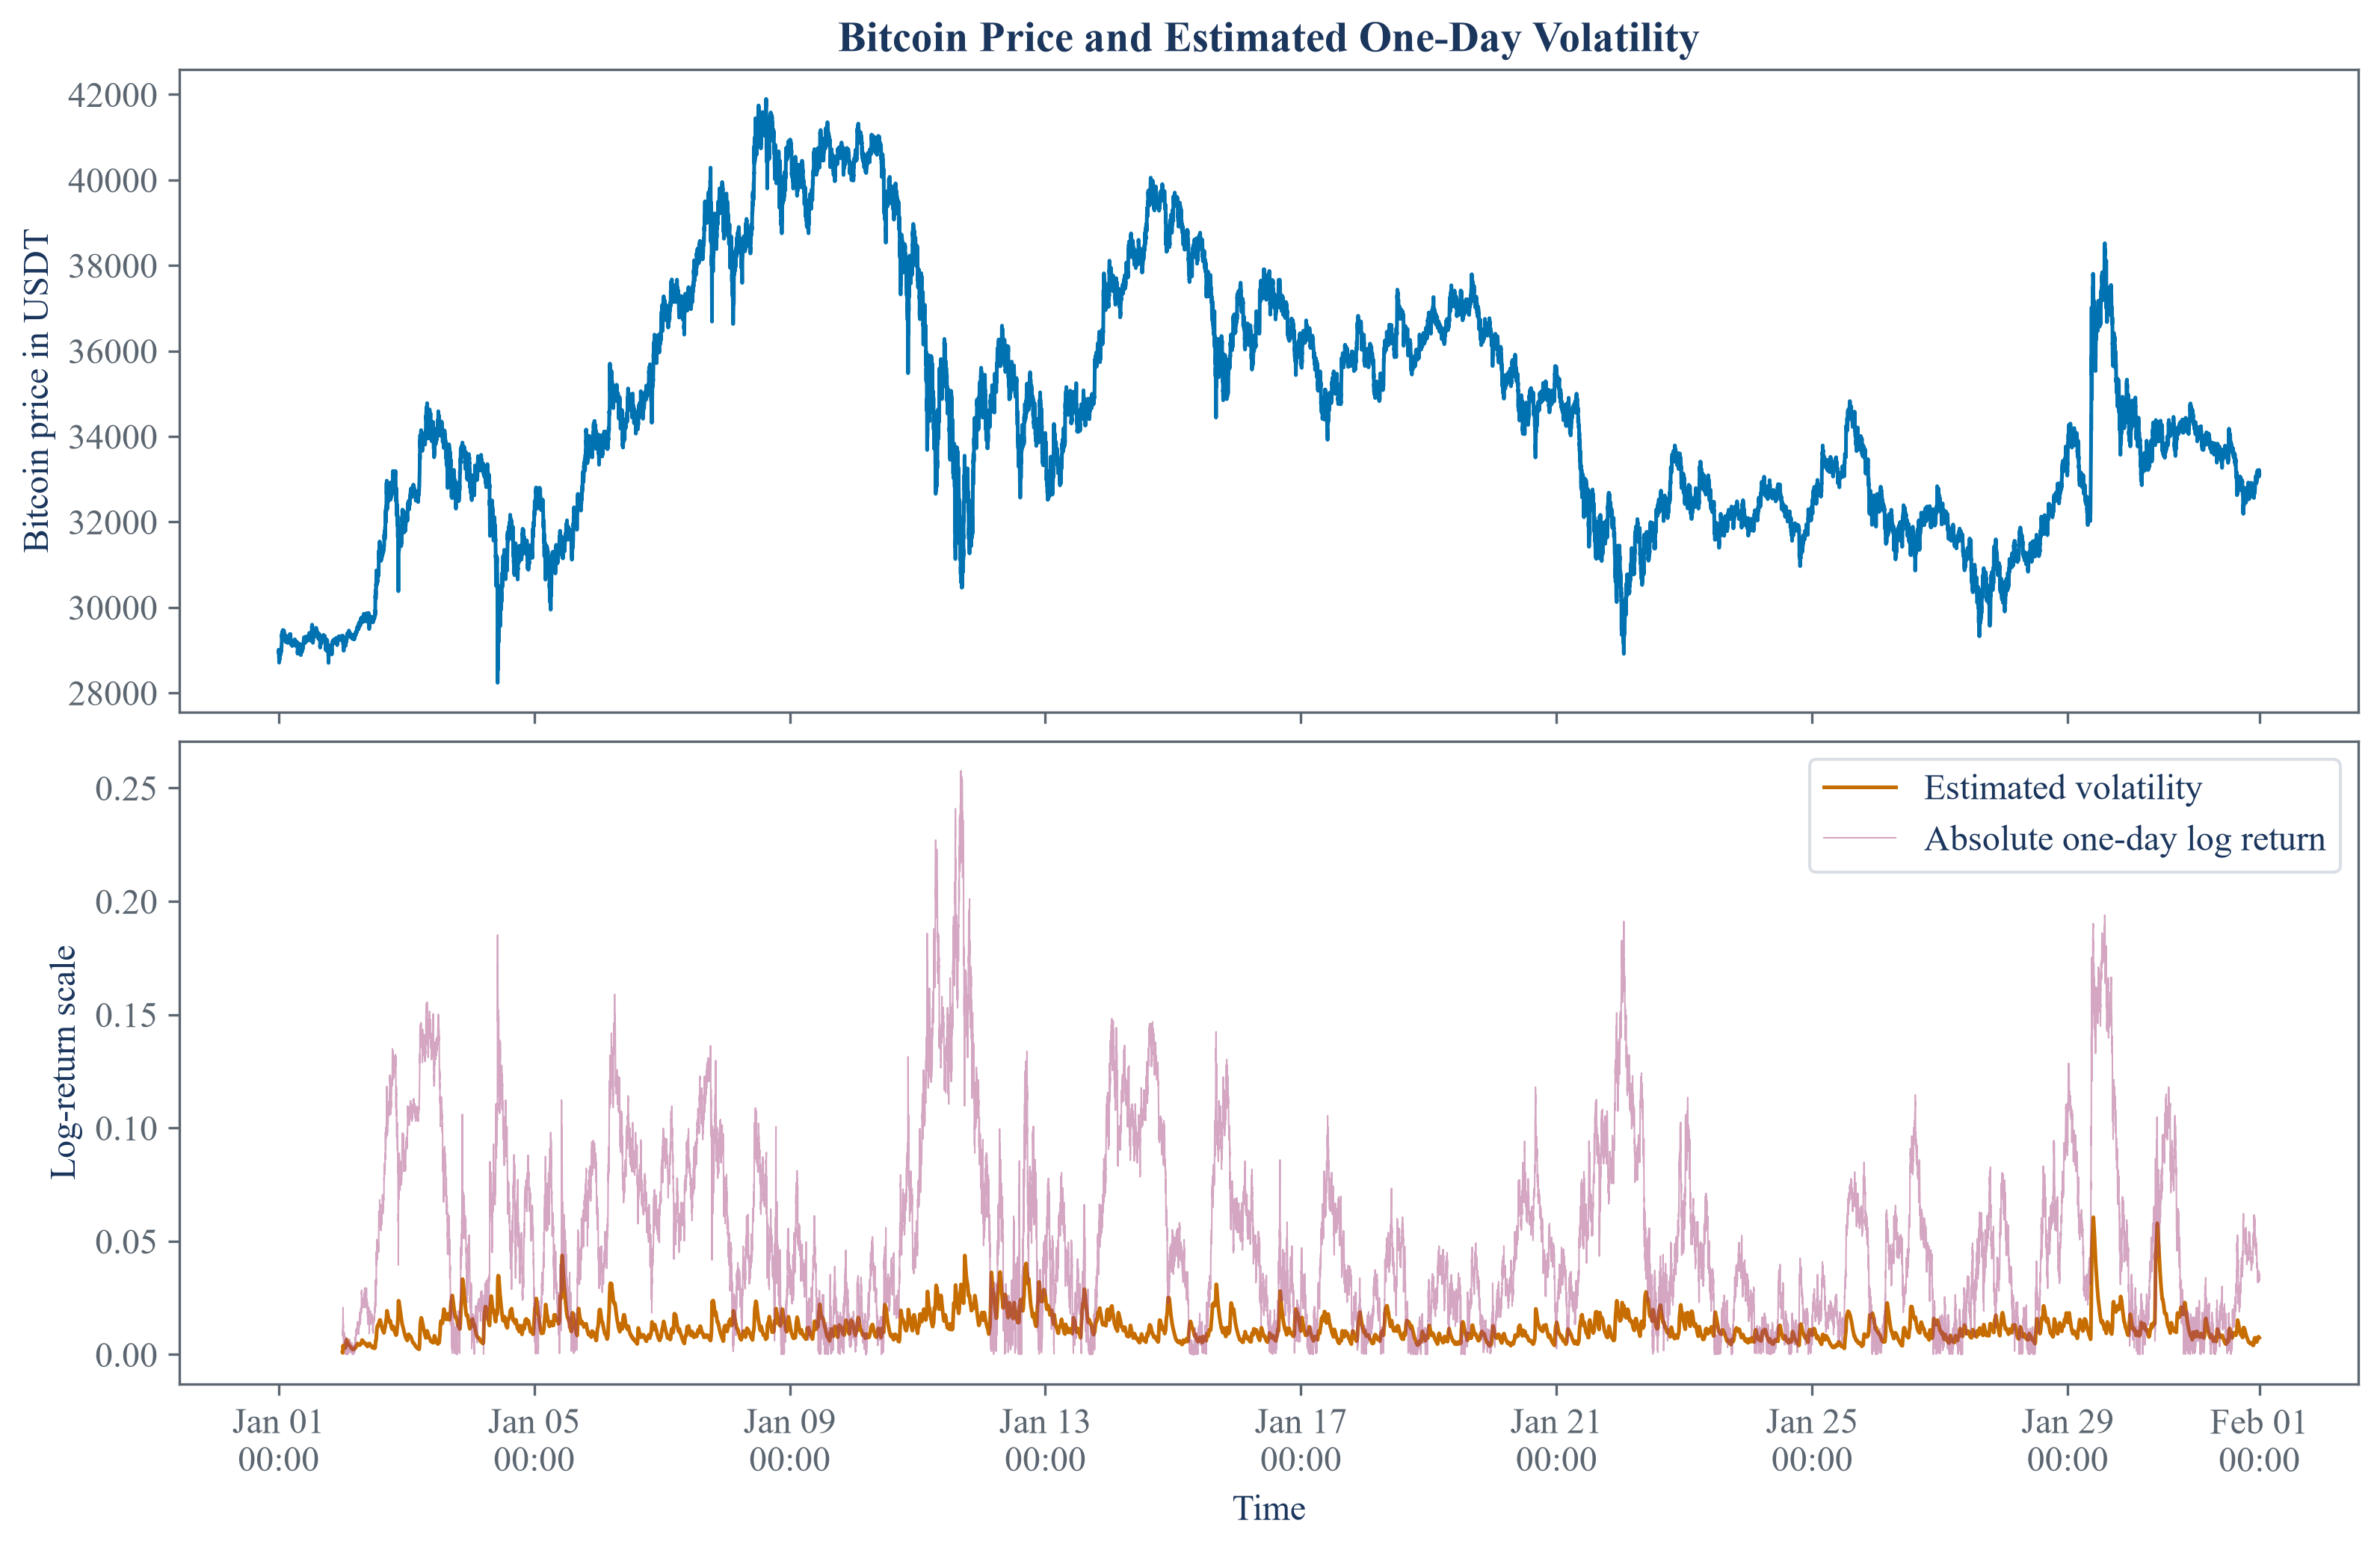
The volatility estimate is formed from earlier returns and sets the scale for event detection and barriers without using the later outcome.
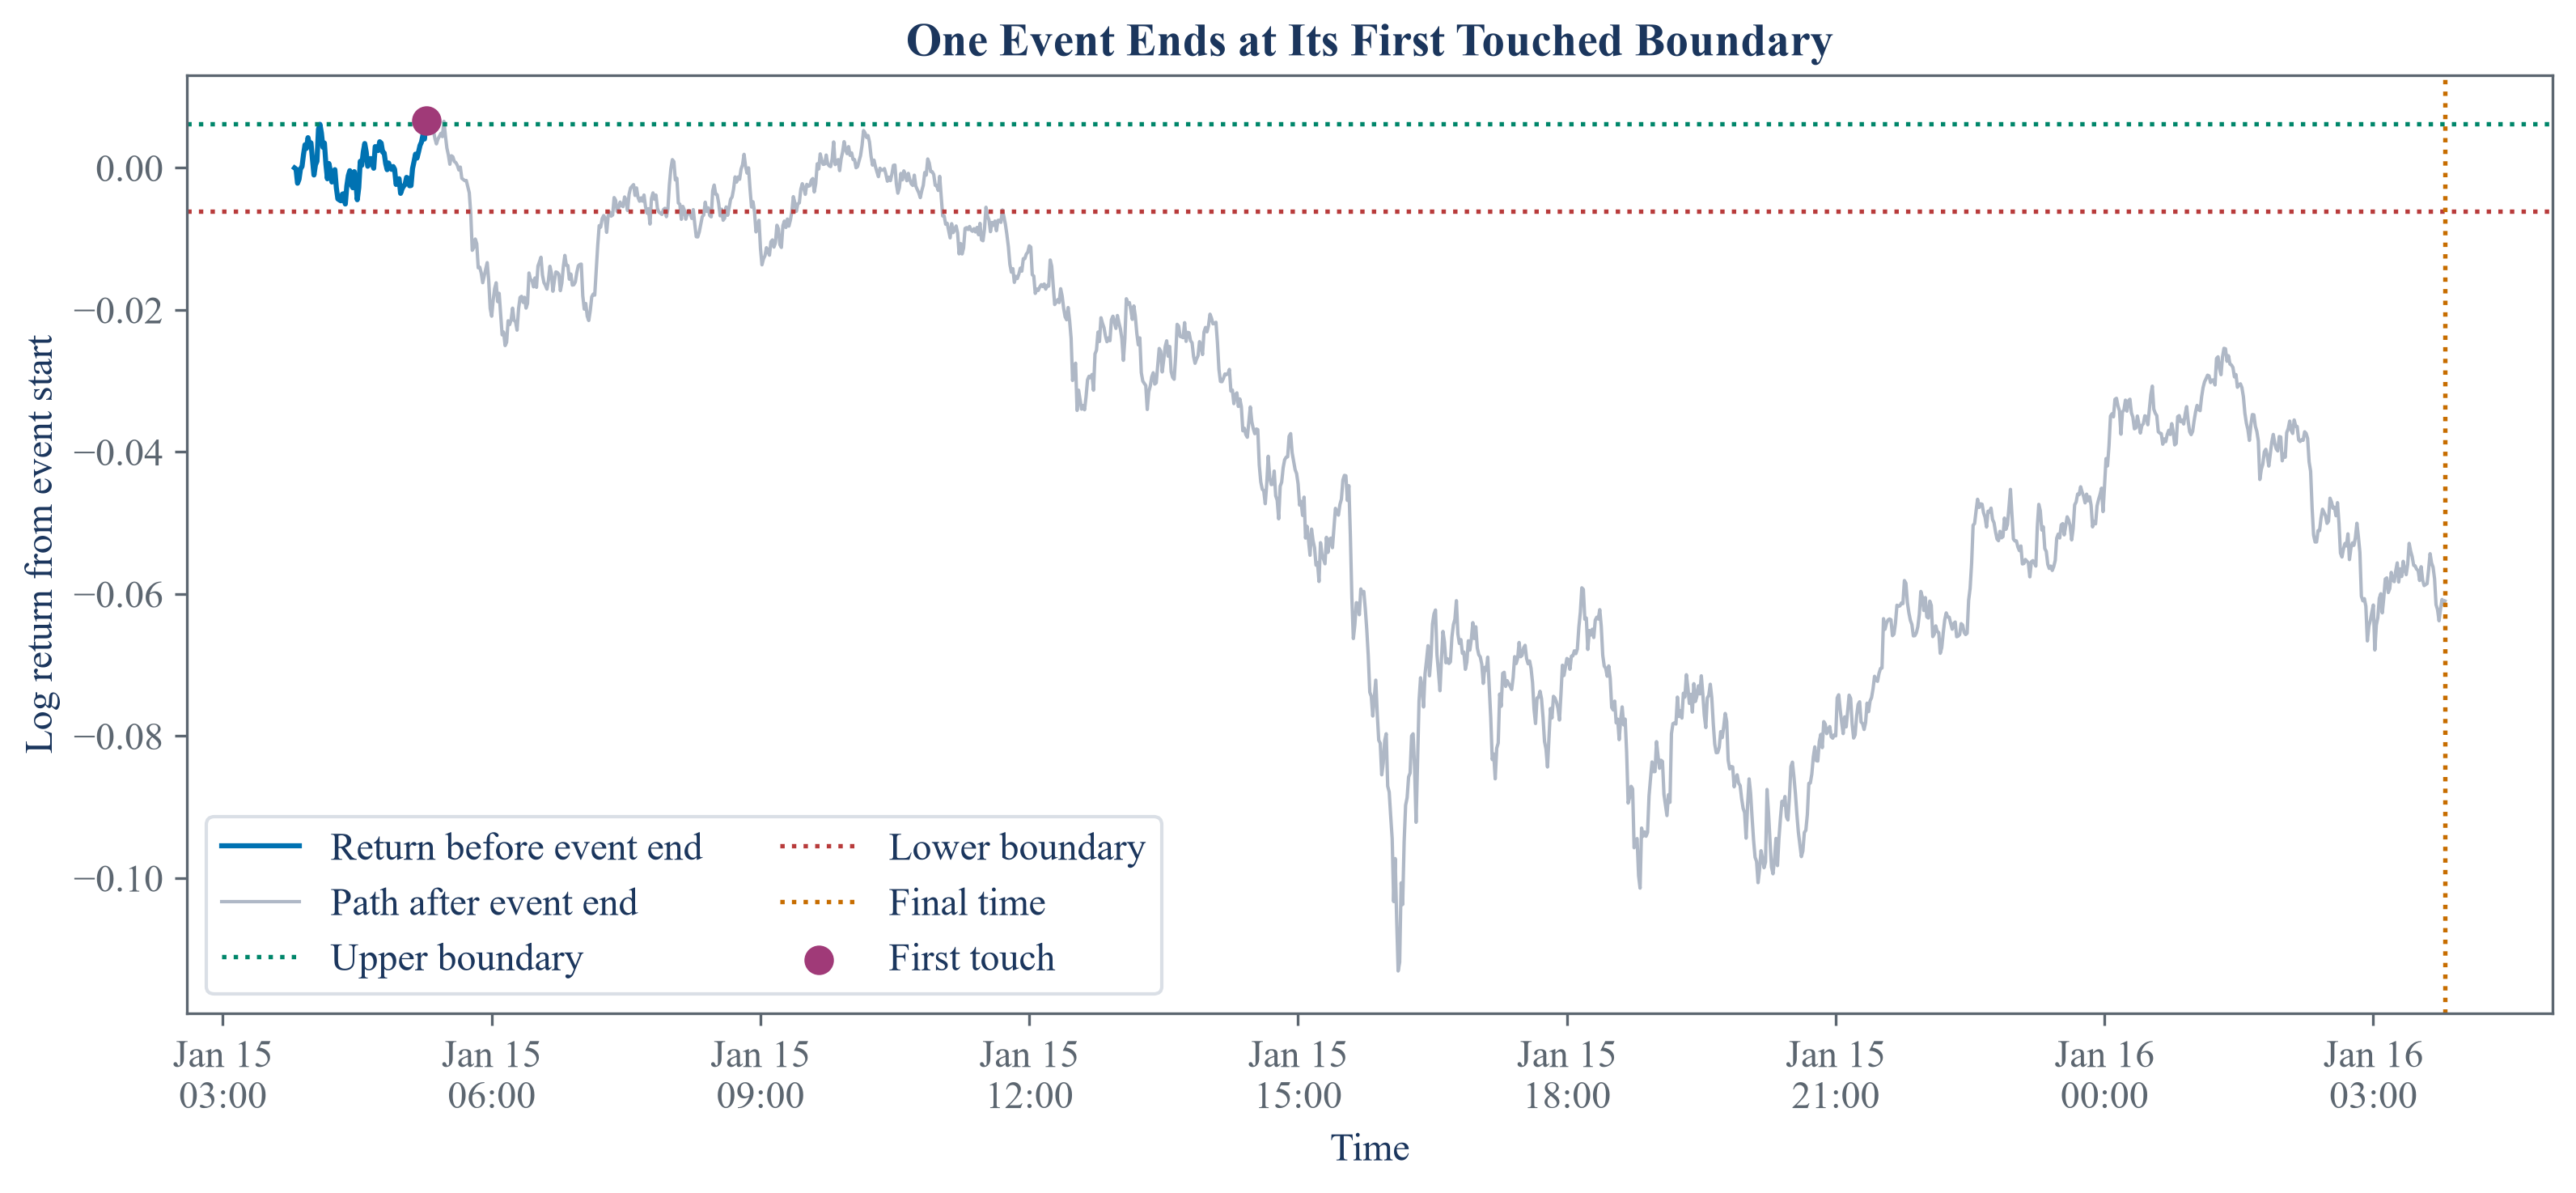
Each event is labeled by its first observed barrier crossing. Paths that reach the time limit before a price barrier receive the neutral outcome.
A label is part of the research design. Different horizons or barrier scales define a different prediction problem and must be chosen before evaluating the result.
Notebooks
| 1. Detecting events with volatility-scaled filters |
| 2. Labeling first-passage events with three barriers |
| 3. Checking labels from meta-labeling and trend scans |