- Published on
Portfolio Choice after Model Search
A portfolio chosen after trying many signals inherits uncertainty from that search. These notebooks connect the recorded search family to selection thresholds and then show how uncertainty in expected returns and exposures changes a constrained allocation.
The central relation
A minimum-variance portfolio with target factor exposures solves
is the vector of portfolio weights, is the asset return covariance matrix, contains the asset exposures to selected factors, and is the desired exposure vector. The objective measures portfolio variance while the constraint fixes the exposures.
How model search changes portfolio evidence
The public allocation shows how the exposure target is achieved across assets. The search-count experiment shows why a result selected from a larger family needs stronger evidence before entering that decision.
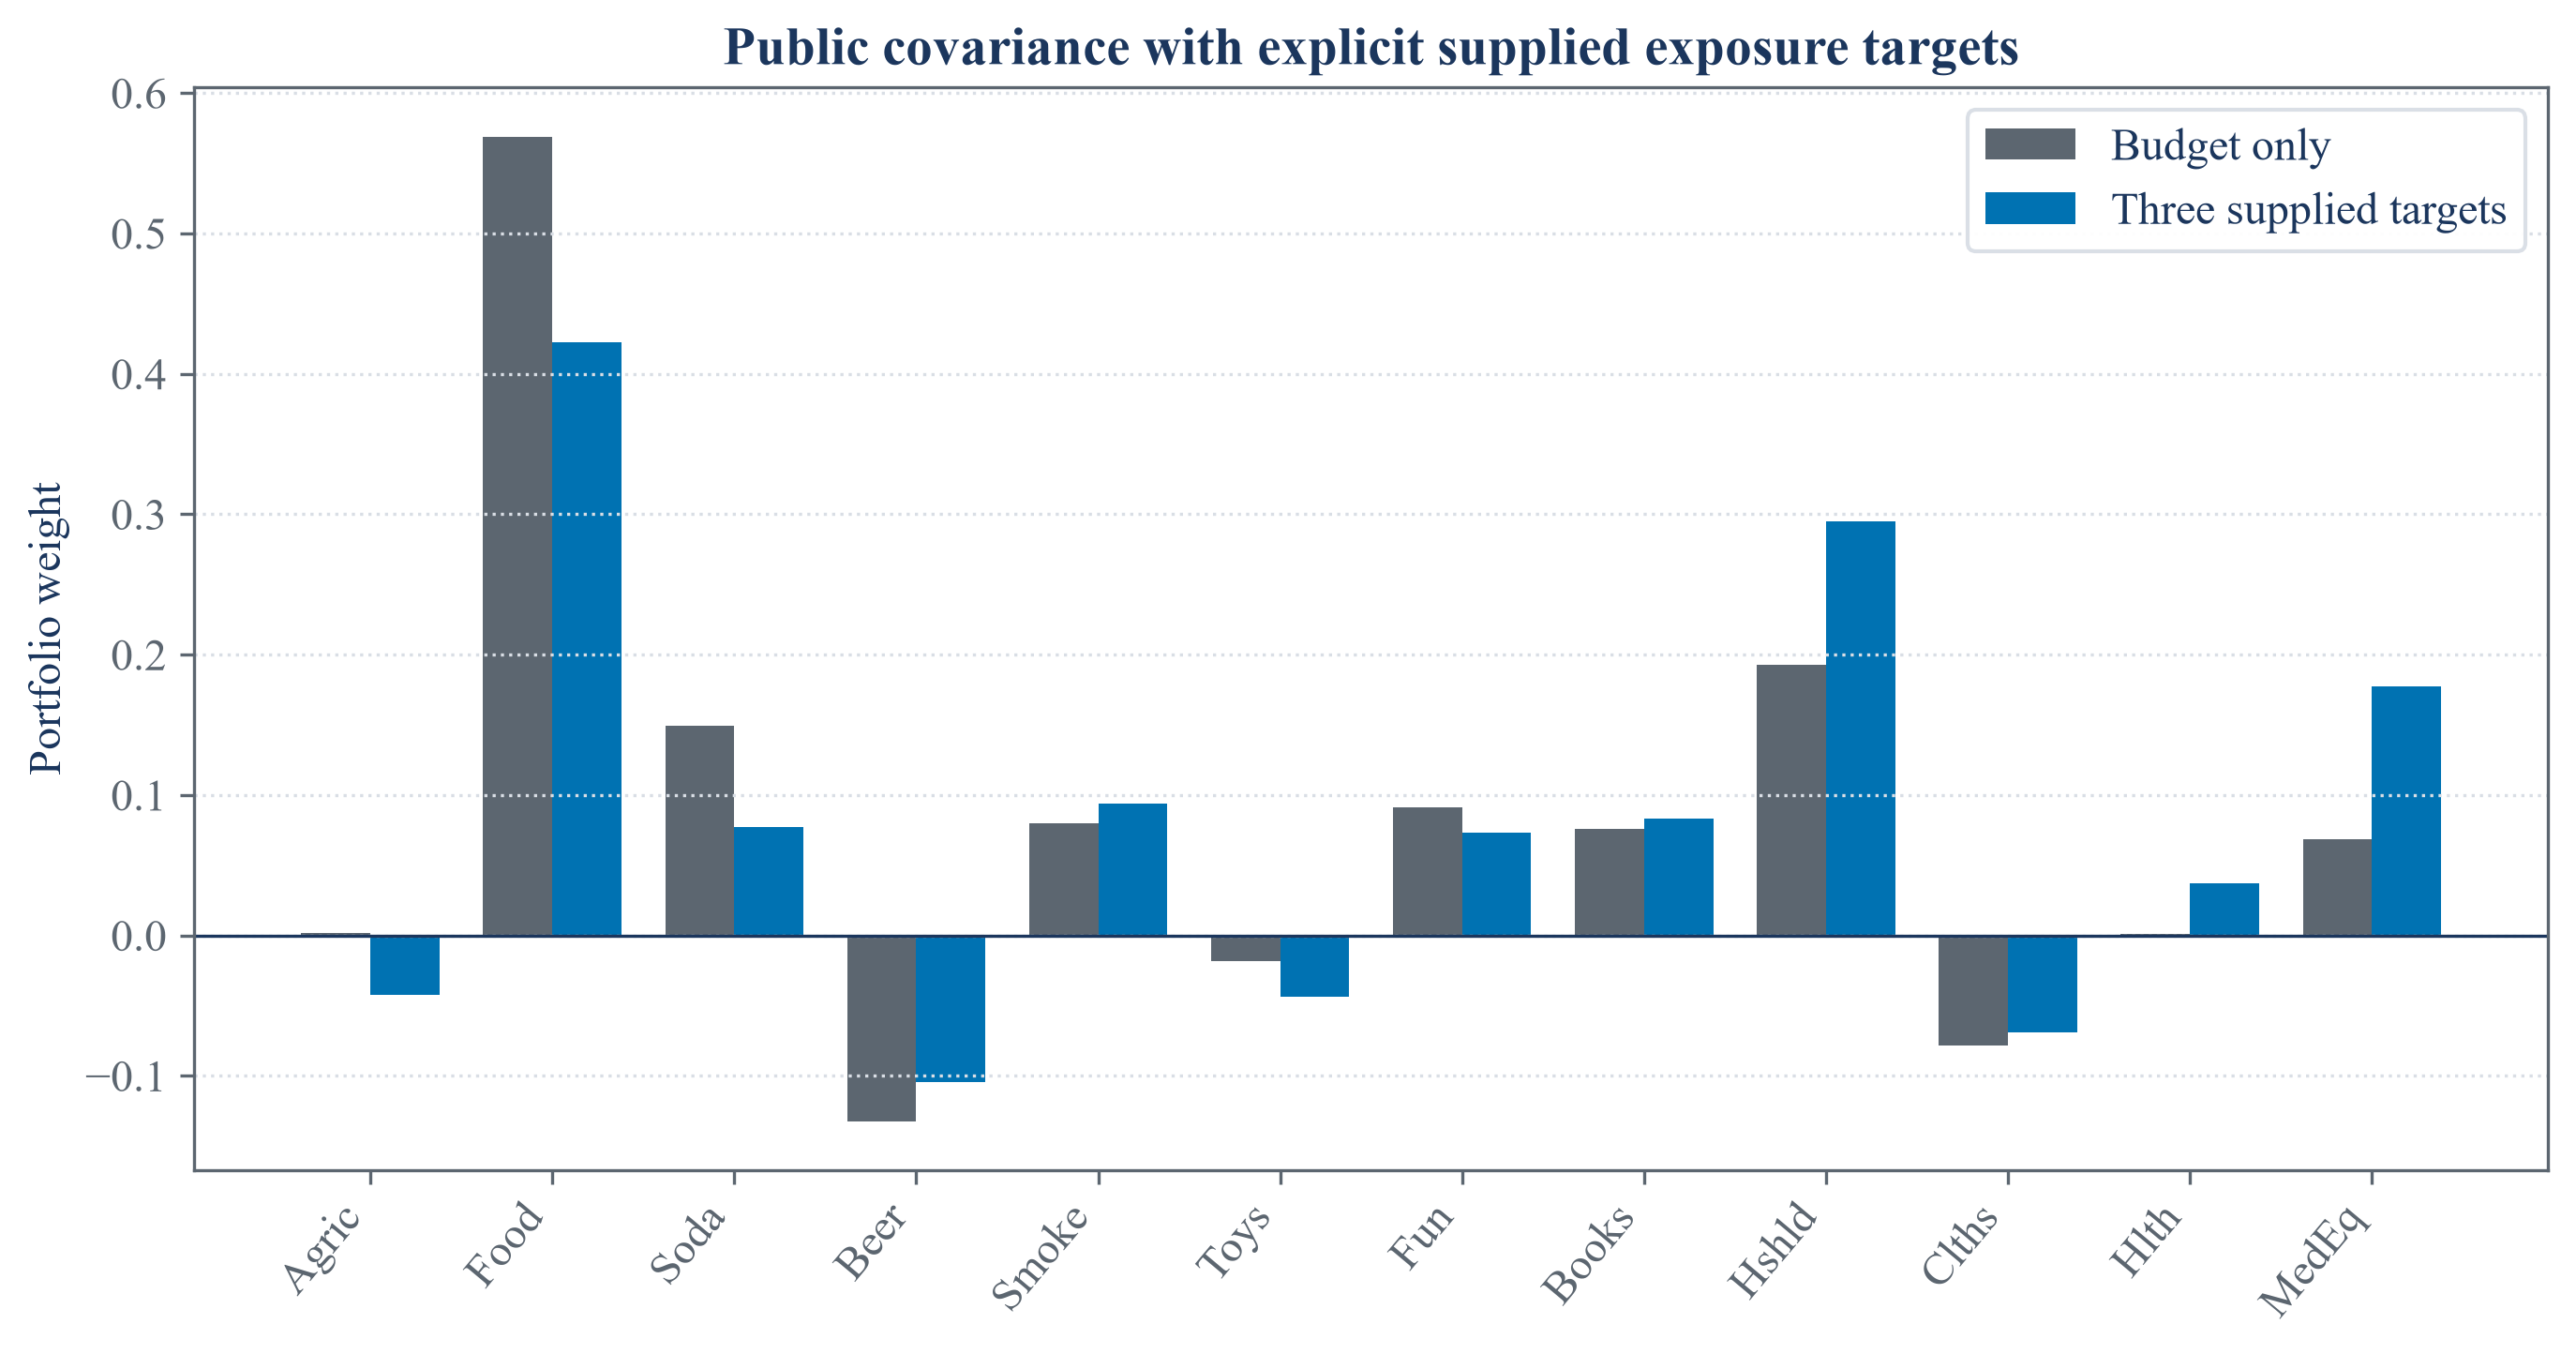
The allocation spreads the target exposures across assets while minimizing estimated variance under the stated constraints.
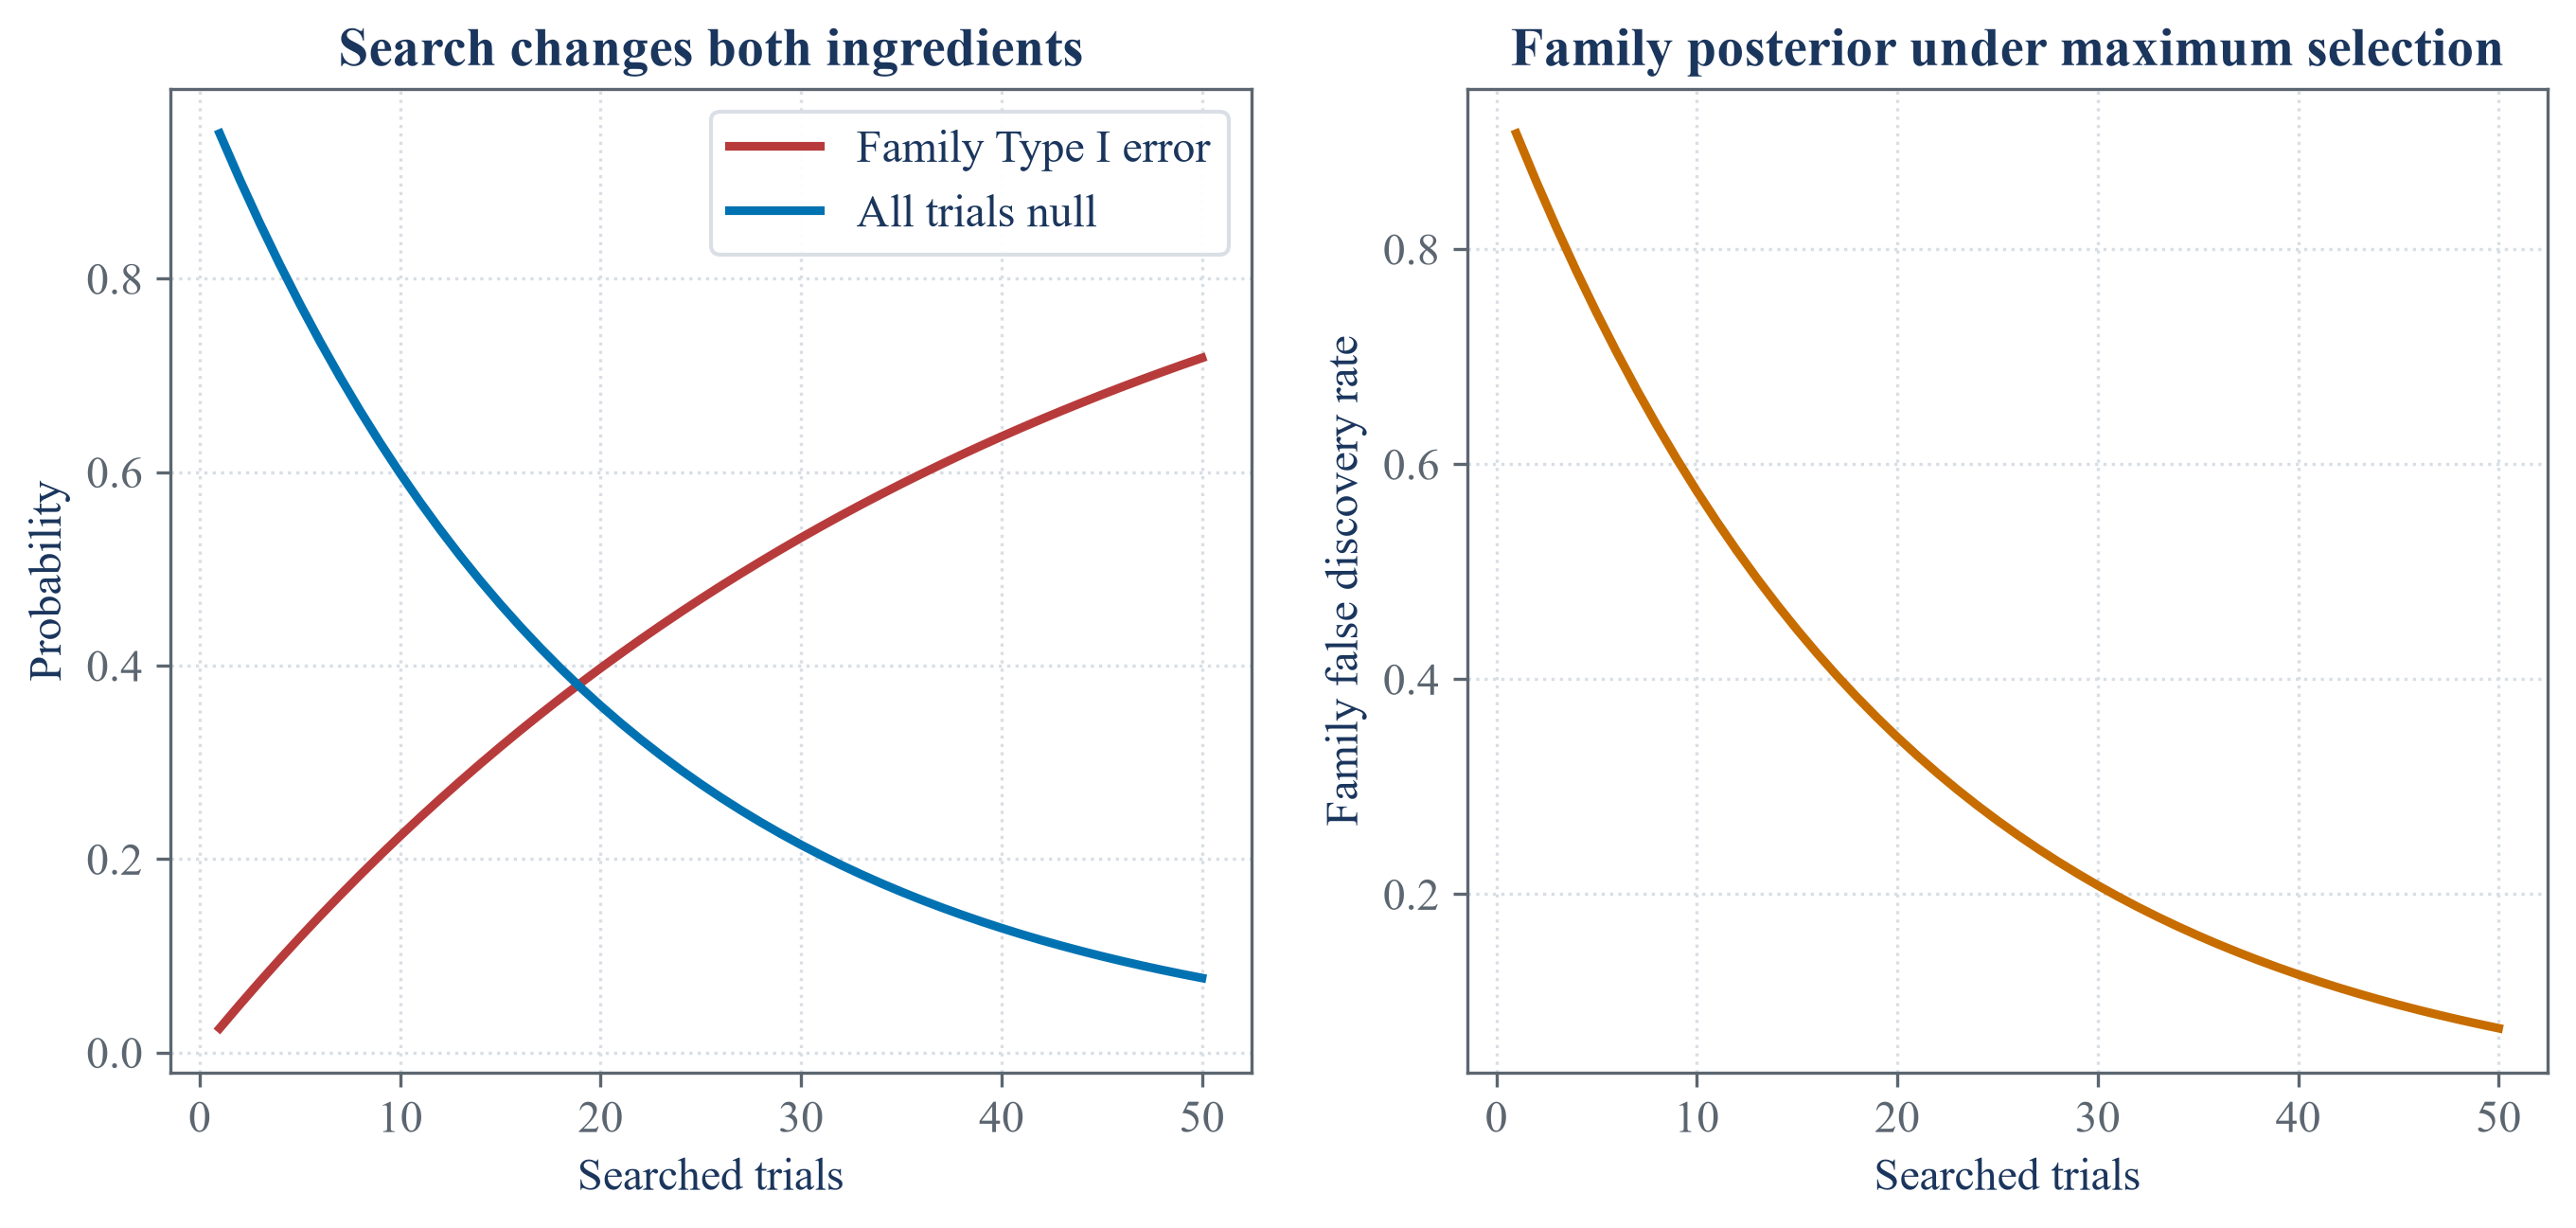
As the recorded search family grows, an isolated extreme result becomes less surprising. The adjustment depends on what was tried, not only on what was retained.
Search adjustment is only as complete as the trial record. Unrecorded specifications cannot be recovered from the selected portfolio alone.
Notebooks
| 1. Minimum-Variance Weights under Target Factor Exposures |
| 2. Allocation Misspecification Diagnostics |
| 3. Selection-Adjusted False Discovery across Searched Trials |